FCA Authorised • No Broker Fees

Independent Private Health Insurance Broker in London

We compare leading UK health insurers to give you clear, honest advice at no cost. We work with Bupa, AXA Health, Aviva, Vitality, WPA and more, helping individuals, families and businesses avoid overpaying or ending up with the wrong cover.

Our team brings over 20 years of combined industry experience, helping clients make confident decisions based on how insurers actually operate in practice.

Speak to an Adviser

No obligation. Recommendations depend on your medical profile and insurer terms.

My Health Protected finalist for Best Individual Health Insurance Advice Firm at the UK Health & Protection Awards 2026

Finalist — Best Individual Health Insurance Advice Firm, UK Health & Protection Awards 2026.

£0
Broker Fees
20+ yr
Combined Experience
Leading UK
Insurers

Why Use an Independent Health Insurance Broker?

Independent, FCA-authorised advice that compares leading UK health insurers for you, at no cost, with a named adviser who stays with you after you buy.

FCA-authorised & regulated

We are authorised and regulated by the Financial Conduct Authority (FCA number 785132) and follow Consumer Duty rules that put your needs first. That means independent advice you can actually rely on.

Leading UK insurers compared

Instead of going to each insurer individually, we do the legwork. We compare policies from Bupa, AXA Health, Aviva, Vitality, WPA, The Exeter and others, matching cover to your medical history, budget and priorities. We aren't tied to one panel of insurers.

No broker fees

You don’t pay us a separate fee for our advice. We’re paid by the insurer when you take out a policy through us. Clients will often pay the same or less than going direct, particularly where we can access preferential rates, discounts or exclusive offers.

A named adviser, before and after you buy

Our job does not end when the policy starts. We help with claims, negotiate at renewal and review your cover each year to make sure it still fits. You get a named adviser you can call, not a generic helpline.

Plain-English advice

Health insurance is full of terms like moratorium underwriting, continued personal medical exclusions and outpatient sub-limits. We explain what matters in plain English so you can make a confident decision, with no obligation to proceed.

London-based, UK-wide

Based in Putney, London, we support clients locally and across the UK. Whether you are in London, England, Scotland or Wales, we are here to help.

Private Medical Insurance From Leading UK Insurers

Read our independent provider reviews →

How Much Does Private Health Insurance
Cost in the UK?

Illustrative monthly premiums for typical UK private health insurance profiles.

Individual
Single Professional
Age 30–35 · Non-smoker · Mid-level cover · London
£55–£85
per month
✓ Most popular profile
Individual
Single Professional
Age 45–50 · Non-smoker · Mid-level cover · Outside London
£70–£110
per month
✓ Often lower than expected
Couple
Two Adults
Both 40s · Non-smokers · Mid-level cover · Any region
£130–£190
per month
✓ Discount vs two singles
Family
2 Adults + 2 Children
Adults 35–45 · Non-smokers · Mid-level cover · Any region
£135–£200
per month
✓ Children often low cost

Illustrative premiums only, not quotes. Your price depends on age, location, medical history and level of cover. See our average cost of health insurance guide.

Get an exact quote for your age, region and cover level.

No obligation. Recommendations depend on your medical profile and insurer terms.

How Our Health Insurance Broker Process Works

Whether you are new to private health insurance or reviewing an existing policy, our structured advice process ensures you have the right cover at a competitive price.

01

Understand Your Current Health Insurance Cover

We review your existing plan in detail—the bits you like and the bits you don't.

02

Review Your Medical History

We assess your health records to see which options are safe for you to move to.

03

Compare Suitable Insurers

We look at Bupa, AXA Health, Aviva, Vitality, and more to find a match.

04

Present Side-by-Side Options

We give you clear, honest recommendations in plain English.

05

Support Beyond the Switch

You deal directly with your insurer for claims. If things aren’t going smoothly, we can step in and help. We’ll also review your cover at renewal.

Ready to start? The first call is free and takes about 10 minutes.

Speak to an Adviser

No obligation. Recommendations depend on your medical profile and insurer terms.

What Our Clients Say

Real feedback from real people we've helped find the right health cover. A selection of recent Google reviews for Patrick, Louis and Riley.

Liz Hawthorne

I was really pleased with the advice and assistance given. A terrific balance of professionalism, efficiency and friendliness from both Riley and Patrick. I would definitely recommend them.

Posted on Google Reviews
Manu Joshi

Really impressed with the service from My Health Protected. Patrick Baxter was brilliant throughout, knowledgeable, patient and focused on getting me the best plan for my needs. No pressure, no upselling, just clear advice and a great result.

Posted on Google Reviews
lua leggett

I dealt with Louis who was excellent in his customer service and a thorough grasp of the market and his product solution. Happy to recommend.

Posted on Google Reviews
William Greig

So pleased with the service we received on switching our health insurance. Riley was very helpful and knowledgeable on the services he could provide. We would definitely recommend.

Posted on Google Reviews
Allegra Taylor

Happy to recommend My Health Protected. From my first conversation with Louis he has been efficient, friendly and knowledgeable. He has made the transition to my new policy as seamless as possible and given me good advice. Thank you.

Posted on Google Reviews
Richard Hough

Patrick was very helpful in navigating me through the various options when transferring out of a work-based private health scheme into a personal policy. He was responsive, knowledgeable and impartial.

Posted on Google Reviews
Read All Google Reviews Read our reviews on Trustpilot

As featured in

Our research and expert commentary in the news.

Private Health Insurance Explained

Choosing private medical insurance is rarely about price alone. The right cover depends on how each insurer handles underwriting and your medical history, what is and is not included, and how claims are dealt with when you need them. Below we explain the essentials — from underwriting and pre-existing conditions to costs, switching, family and business cover. For a fuller overview, see our private health insurance guide.

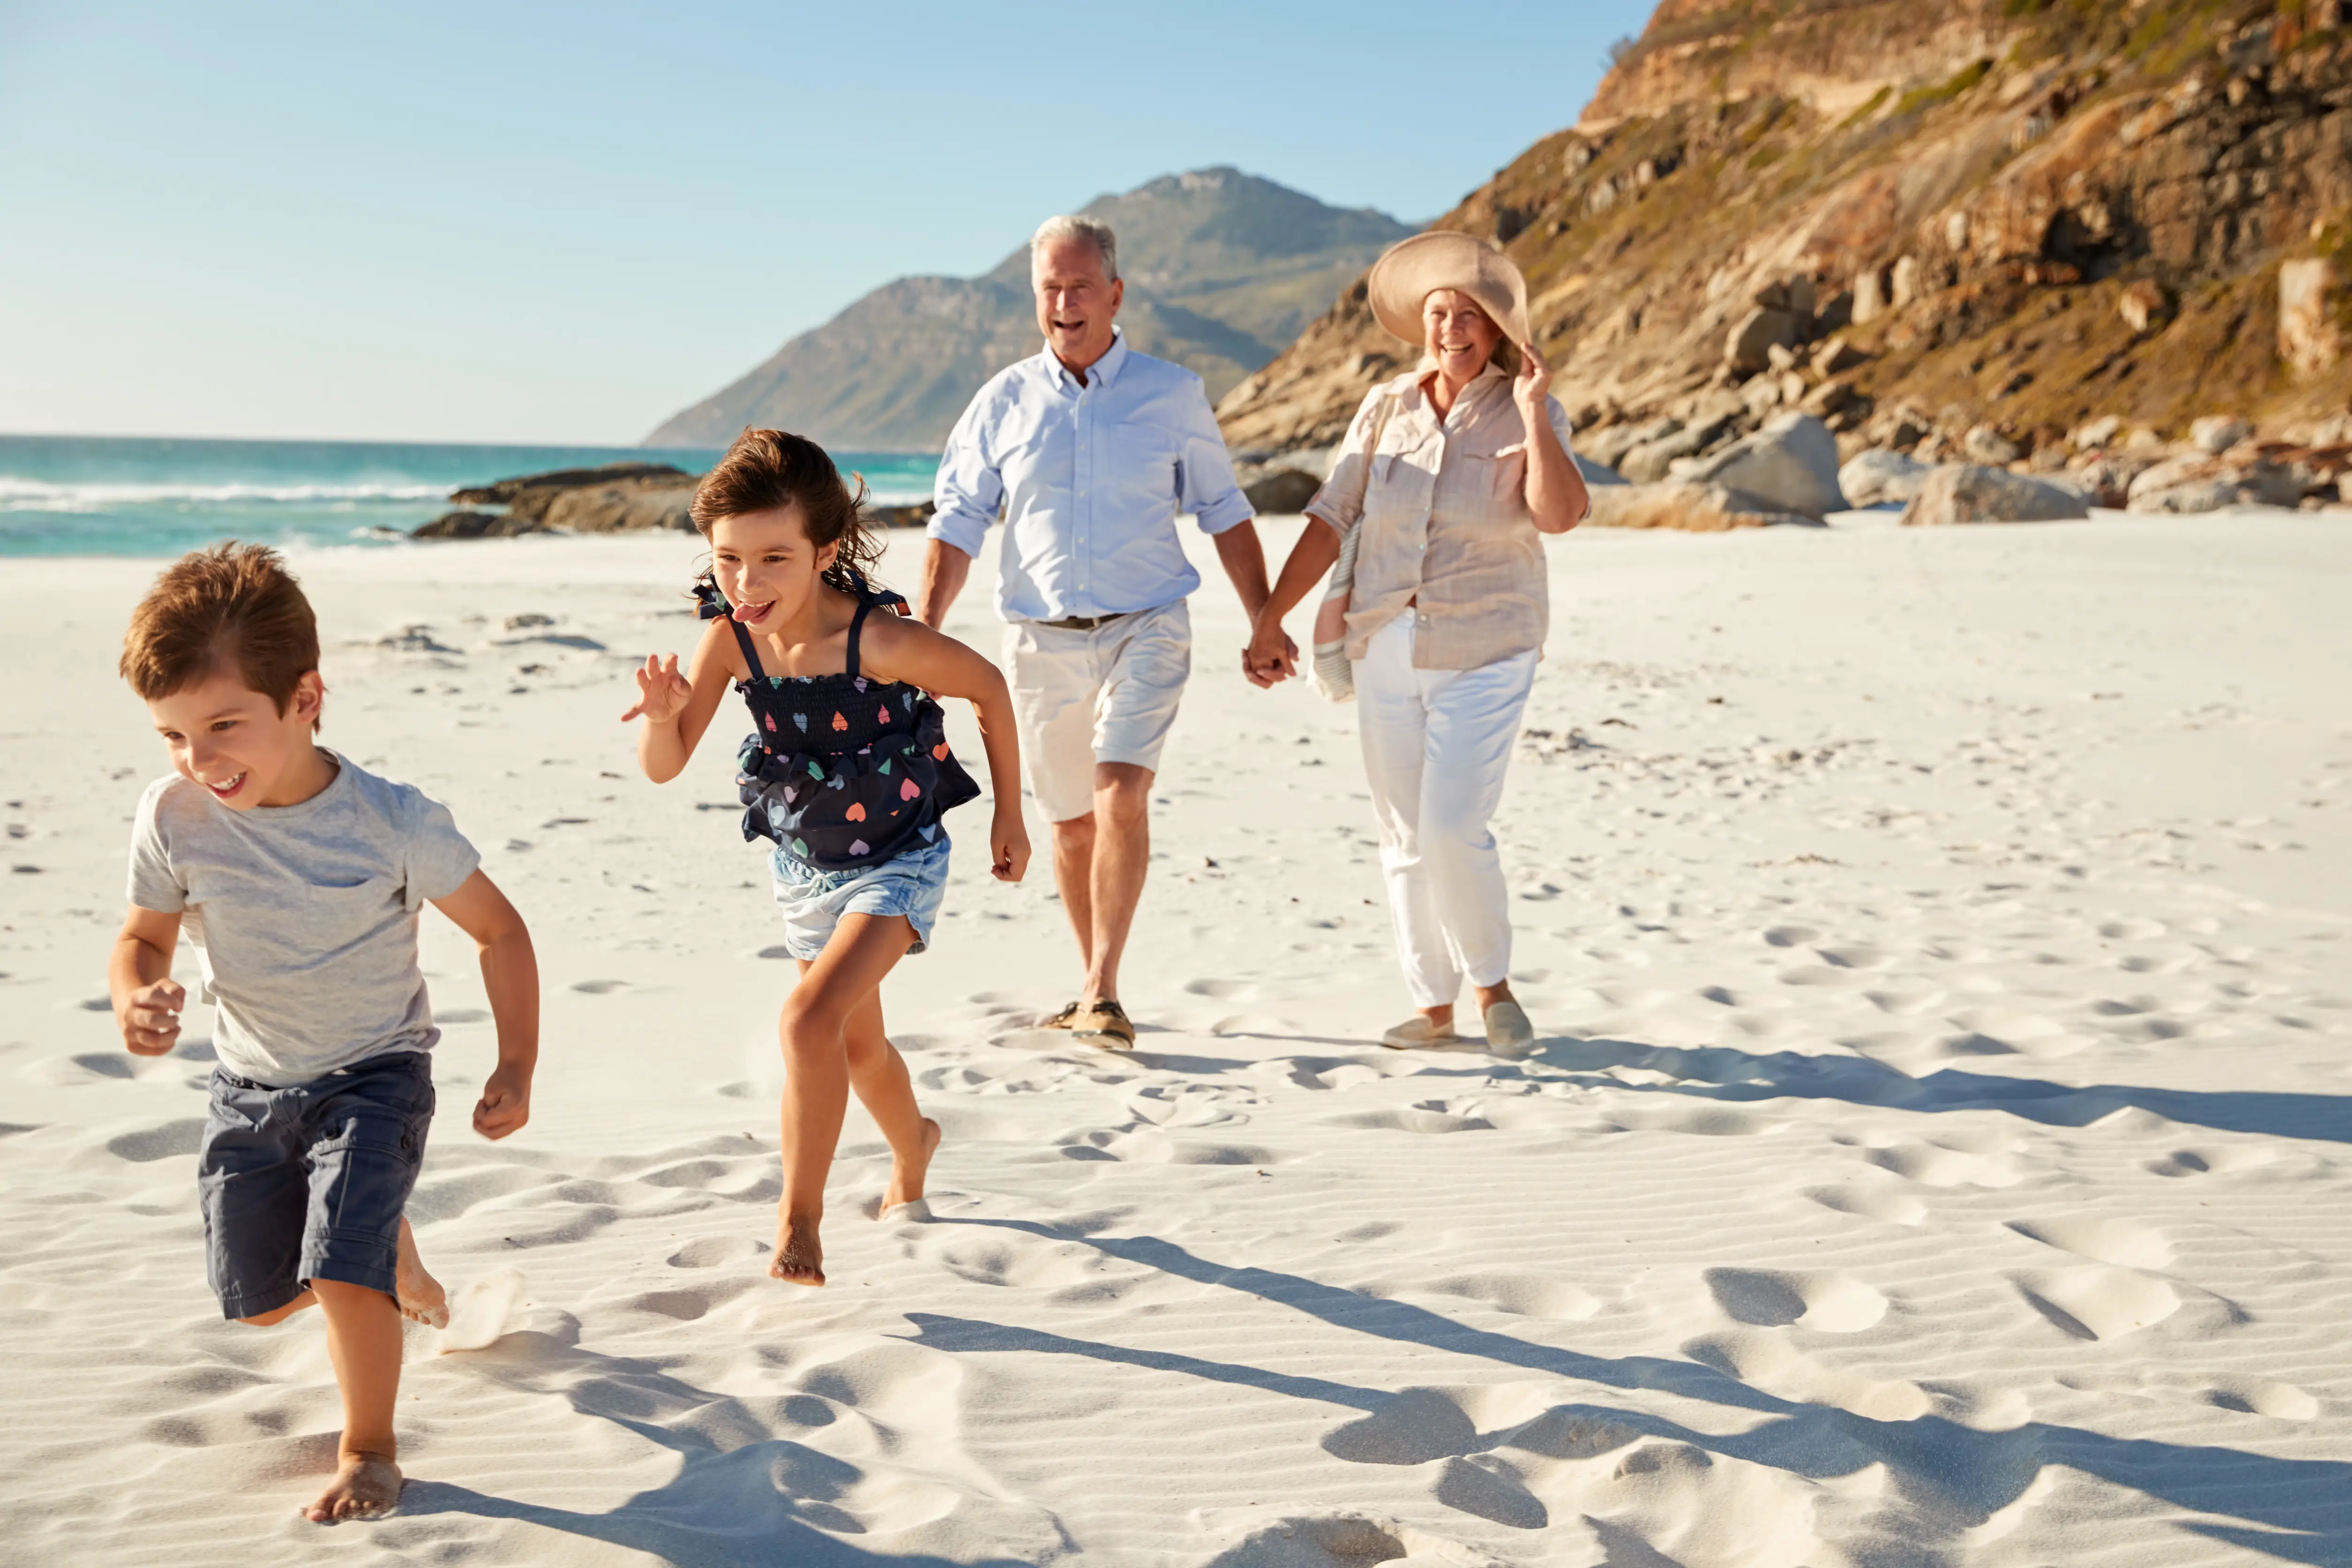
Family protected by private health insurance enjoying the beach together — cover for all ages from an independent UK broker

What Does Private Medical Insurance Actually Cover?

Most people take out PMI to skip NHS waiting times for a referral, scan or operation. A standard plan usually includes inpatient care in private hospitals, outpatient cover for specialist consultations and diagnostic tests, physiotherapy, mental health cover, cancer cover including drugs not yet available on the NHS, and digital GP appointments.

Outpatient limits and mental health support vary widely by insurer, which is why two plans at a similar price can behave very differently when you claim.

Underwriting, Pre-Existing Conditions and Your Medical History

Underwriting is how the insurer decides what it will and won't cover based on your health. With full medical underwriting you give your health details at the start, so you know what is covered from day one.

With moratorium underwriting you give no details upfront, but conditions from your recent past are excluded for a set time (usually two years). Pre-existing conditions are typically excluded unless an insurer offers medical history disregarded terms, which some do. We check how each insurer handles your history so there are no nasty surprises at claim time.

Switching Your Plan Without Losing Protection

Many people stay with the same policy for years because they are afraid of losing cover for a past illness. When we help you switch, we look at continued personal medical exclusions and continued medical history terms, which let you move insurer while keeping your existing protection.

We manage the whole move and make sure your new start date matches your old plan ending.

Individual Health Insurance

Whether you are self-employed, buying private cover for the first time or leaving an employer scheme, we compare individual plans from leading UK health insurers and match the level of cover to your medical history, budget and priorities.

When you leave an employer your group cover typically ends, and acting before it does protects your medical history and avoids gaps in cover.

Family Health Insurance Plans

A family health insurance plan is often better value than separate policies, because most insurers offer discounts when you add a partner or children.

We compare options across Bupa, AXA, Aviva, Vitality and others to find the right balance of cover and cost for your household, from faster diagnosis to specialist treatment and mental health support where included.

Business Health Insurance for Small Business Owners

For most small businesses, the main reason to add a business health insurance plan is that it reduces sickness absence and helps staff get back to work faster after treatment.

We work with employers to match cover, from digital GP through to mental health support, to your team size, age profile and budget, without paying for modules you will not use.

Comparing the Top UK Health Insurance Providers

We compare Bupa, AXA Health, Aviva, Vitality, WPA and The Exeter. Each insurer differs in how it handles claims, underwriting and long-term value.

Some are stronger on mental health support, others reward staying active. By looking at your medical history, we match you to a provider whose strengths line up with what you are most likely to claim for.

We Don't Just Look at the Monthly Cost

We look at what you get for your money. Premiums depend on your age, location, level of cover and medical history, but two policies at the same price can differ significantly in how they handle claims, what they exclude and how they treat you at renewal.

Choosing based on price alone is one of the most common mistakes we see, and that is where independent advice makes the difference.

Meet the Team

Our FCA-authorised brokers work across the major UK health insurance providers day in, day out. Practical, plain-English advice. No jargon, no sales pressure.

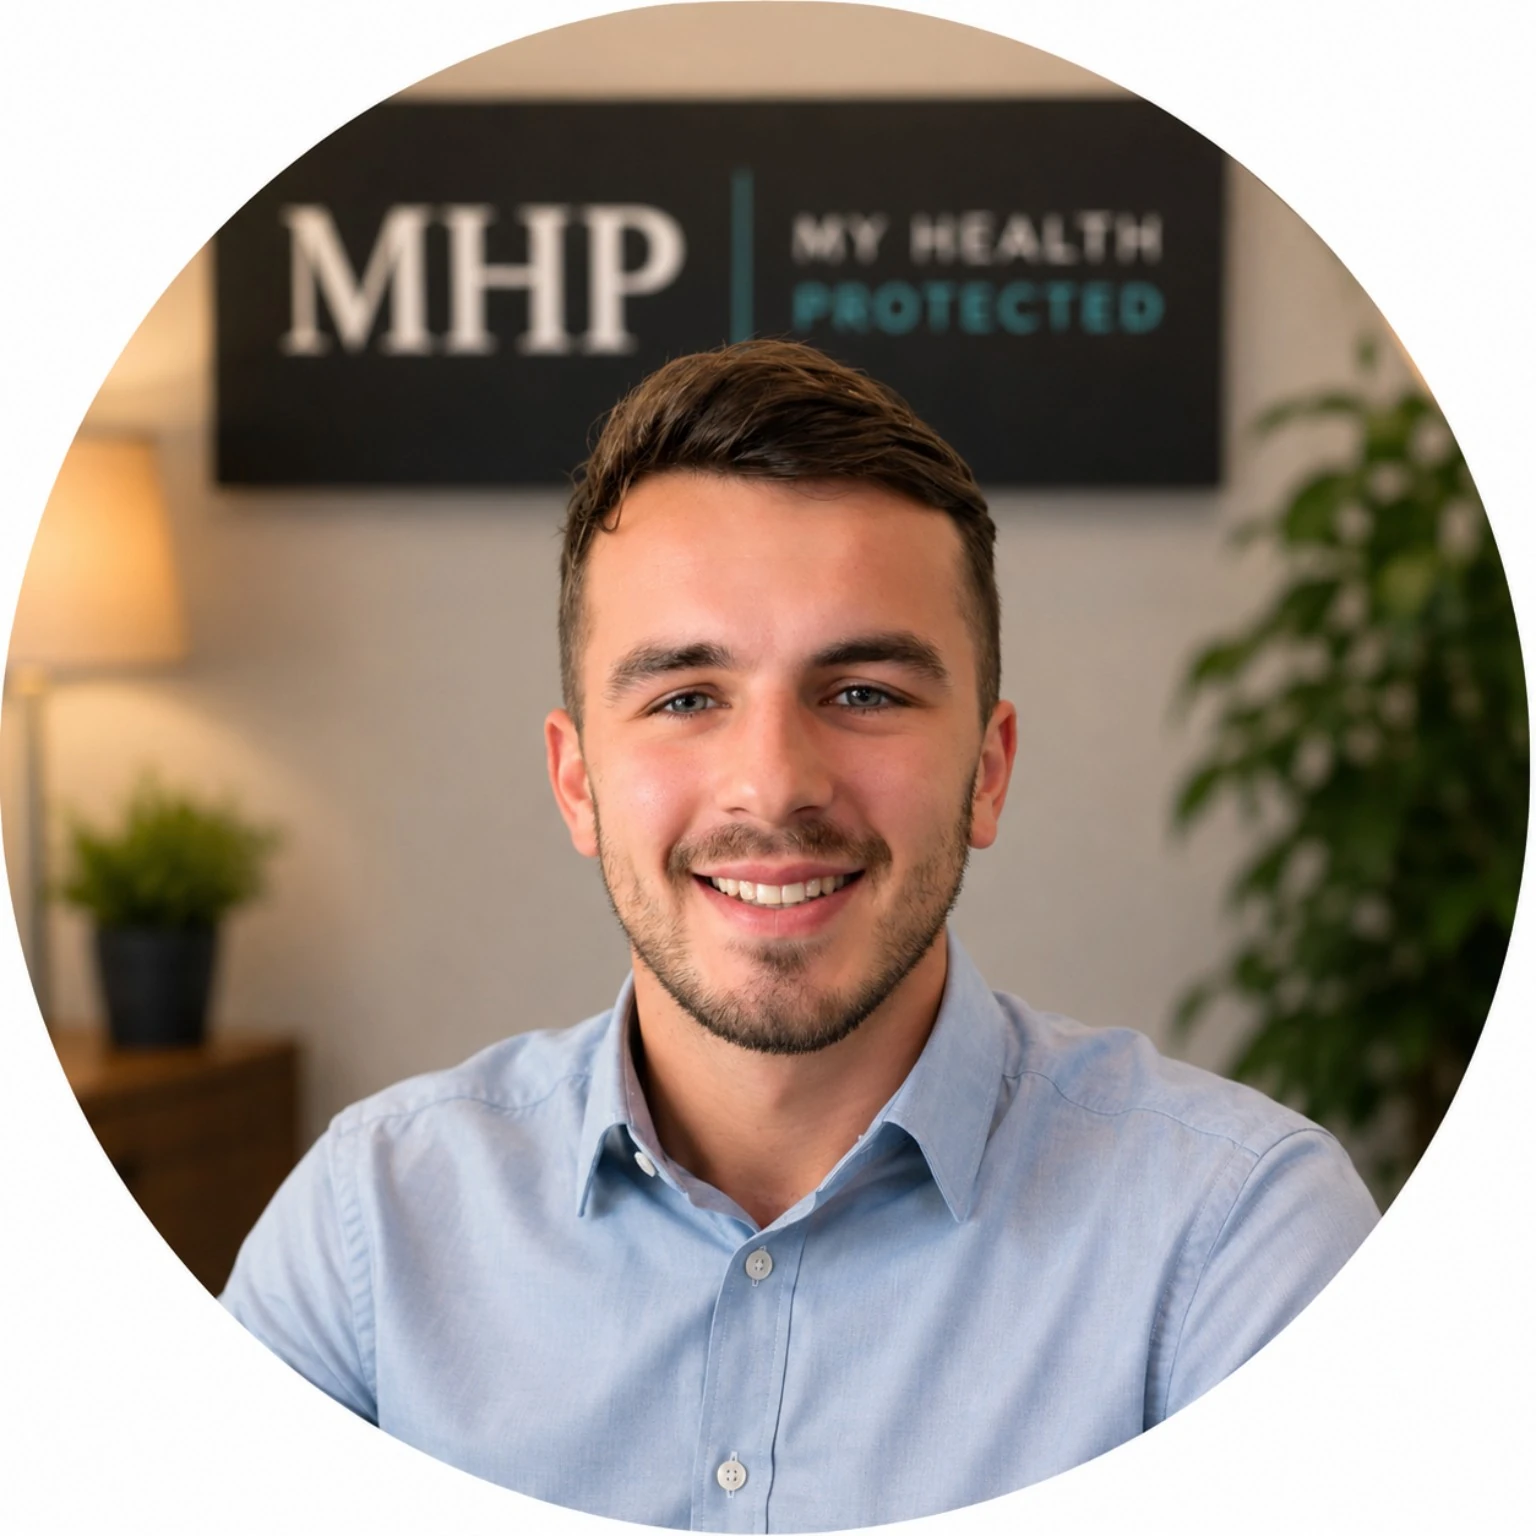
Patrick Baxter, Managing Director and Founder of My Health Protected, independent UK health insurance broker

Patrick Baxter

Managing Director & Founder

Patrick has led My Health Protected for over 10 years. With six years previously at AXA, he brings over 15 years of UK PMI experience. He focuses on giving each client clear, independent advice grounded in how insurers actually handle claims and renewals.

LinkedIn →
Sadie Sansford, Business Development Director at My Health Protected in London

Sadie Sansford

Business Development Director

Sadie has been with us for over seven years and leads our business-development work. She focuses on SME and corporate schemes, helping employers compare insurers on cover, claims handling and renewal experience.

LinkedIn →
Louis Nichols, Lead Health Insurance Broker at My Health Protected in London

Louis Nichols

Lead Broker

Louis leads the broking team and looks after a large book of individual and family clients year on year. His focus is matching cover to medical history and explaining the trade-offs between insurers in plain English.

LinkedIn →
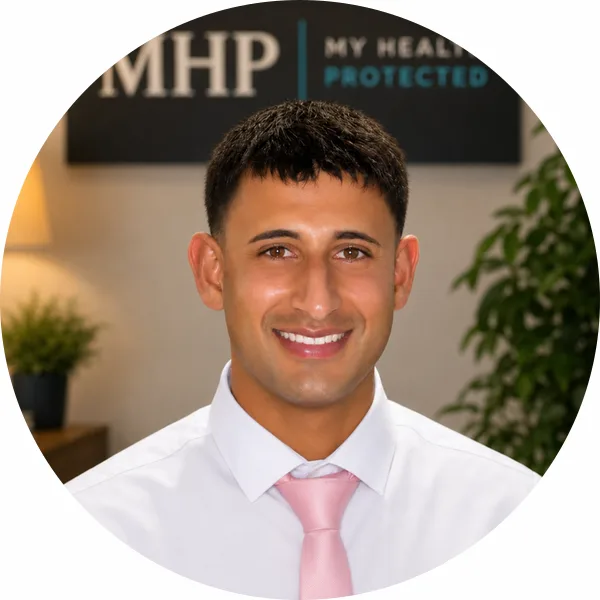
Riley Walia, Senior Health Insurance Broker at My Health Protected

Riley Walia

Senior Broker

Riley helps clients find the right cover with simple, clear advice. With a background in Business Economics, he is excellent at matching Medical Plans to people's needs.

LinkedIn →
Sarah, Customer Care at My Health Protected

Sarah

Customer Care

Providing friendly support for appointments, enquiries and day-to-day client assistance.

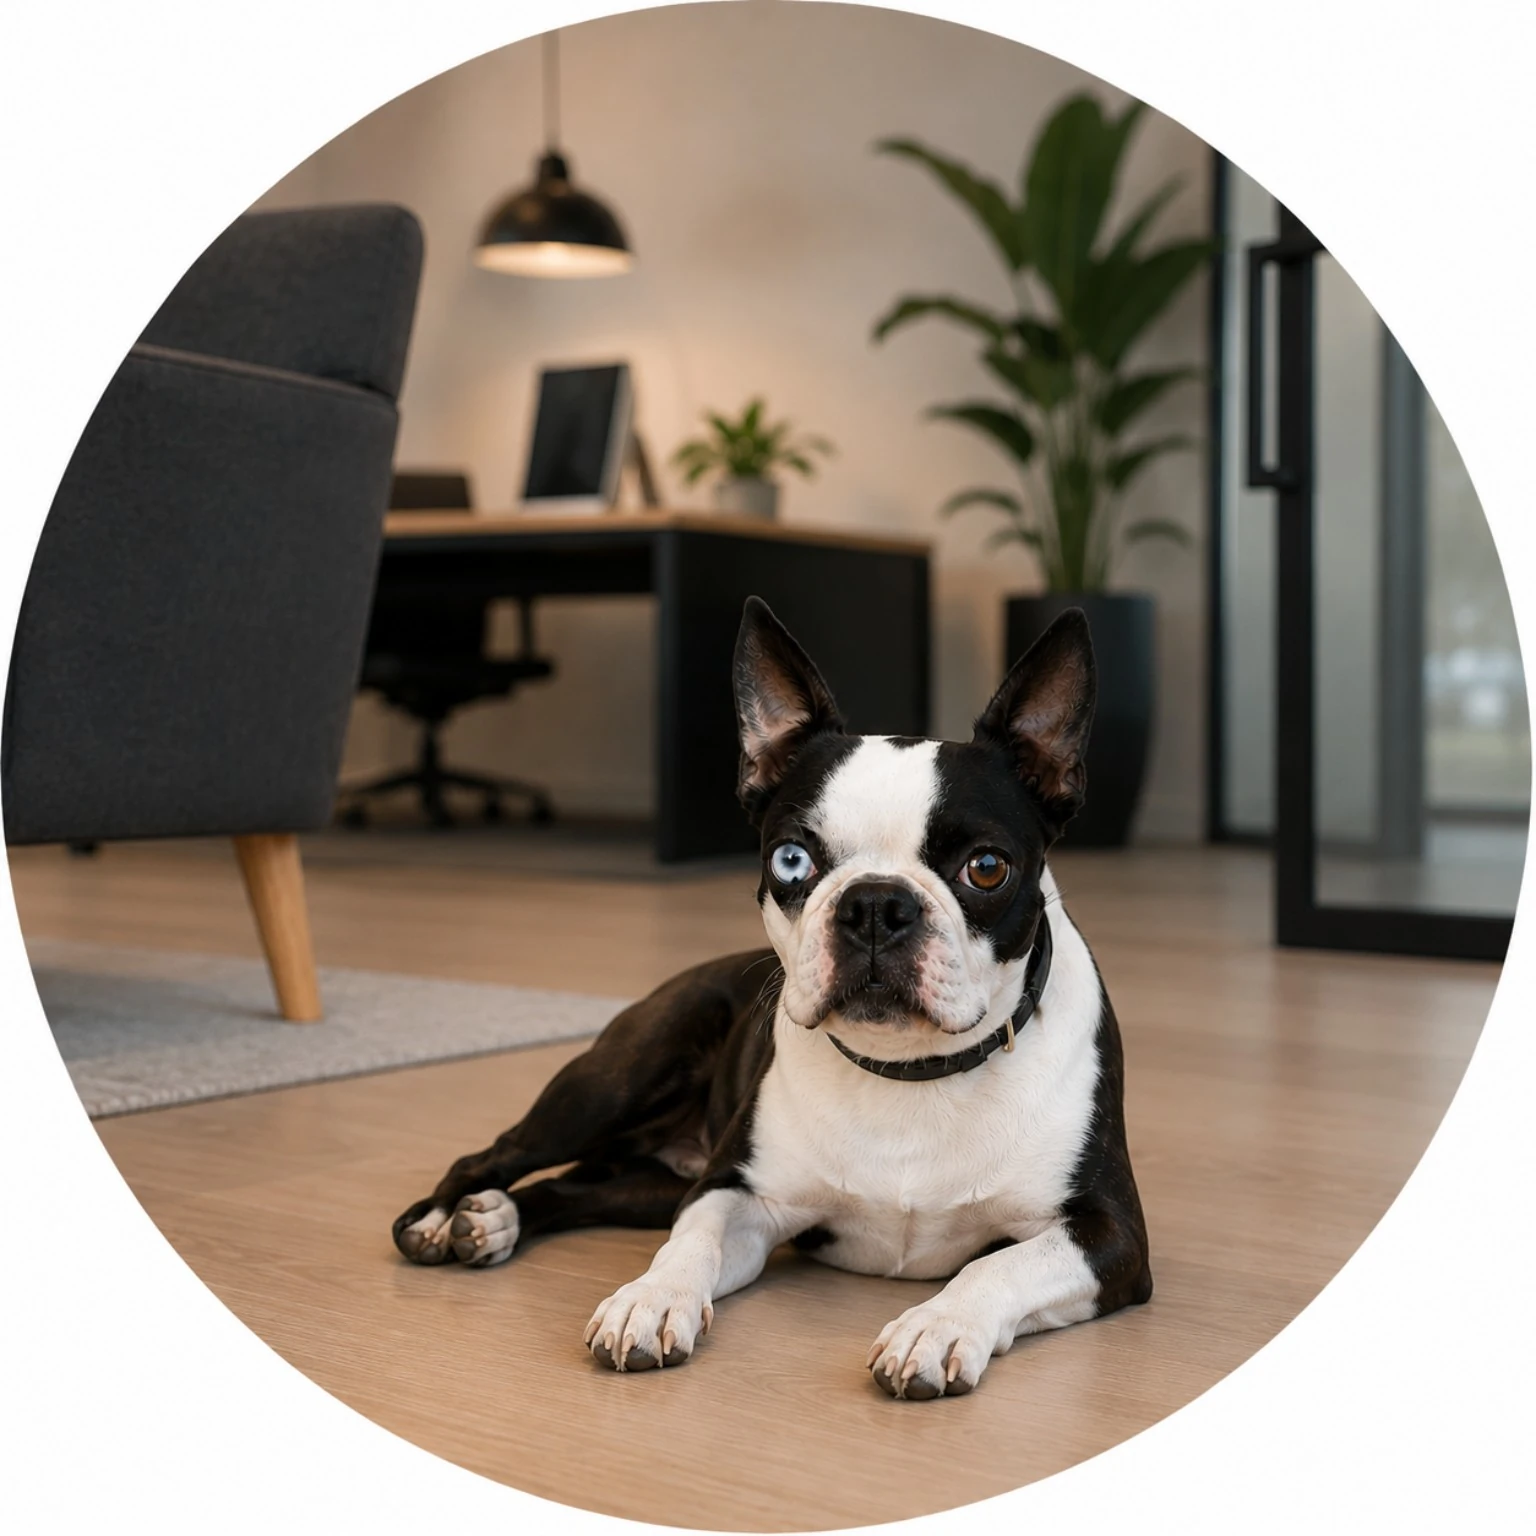
Rudy, office dog and Chief Barketing Officer at My Health Protected

Rudy

Chief Barketing Officer

Rudy keeps spirits high in the office. Her duties include tail wags, walk breaks, and providing "unsolicited feedback" during video calls. Every plan gets Rudy's "bark of approval."

LinkedIn →

Like what you see? Speak to one of our advisers on 0203 859 1822, or read more about My Health Protected.

Common Questions About Using a Health Insurance Broker

What is private health insurance?

Private health insurance pays for private medical treatment so you are not reliant on NHS waiting lists. It covers things like specialist consultations, diagnostic tests, surgery and hospital stays. You choose the level of cover and which conditions and treatments are included.

What does private health insurance cover?

Most policies cover inpatient treatment, outpatient consultations and diagnostics, and mental health support. Some also include private GP access, physiotherapy and cancer care. What is included varies significantly by insurer and policy level. An independent broker can explain the key differences in plain English.

Does private health insurance cover pre-existing conditions?

Generally, private health insurance covers new conditions that arise after the policy starts. Pre-existing conditions are typically excluded unless the insurer offers medical history disregarded (MHD) underwriting, which some do. An independent broker can advise which insurers and underwriting options give you the best chance of meaningful cover.

How much does private health insurance cost in the UK?

Costs vary depending on your age, location, the level of cover you choose and whether you smoke. As a rough guide, individuals in their 30s typically pay from £55-£85 per month for mid-level cover through a broker. Families and older applicants pay more. Independent broker advice is free and provides an accurate comparison for your specific circumstances.

Is it worth switching health insurance?

It depends on your circumstances. If your renewal has increased significantly, or if your cover no longer matches your needs, switching can save money and improve your protection. However, switching is not always the right answer. A structured independent review gives you clarity either way.

Will I lose cover if I switch health insurance provider?

Not necessarily. Many insurers offer continued medical history or medical history disregarded terms when switching. However, this is not automatic and depends on the insurer and your medical history. Switching without proper advice can result in restrictions on cover, which is why independent guidance matters.

Can I switch health insurance after making a claim?

Yes, you can switch at any time, including after a claim. However, the condition you claimed for may be treated differently by a new insurer depending on the underwriting method. An independent broker will assess this before recommending any move.

What happens to my health insurance when company cover ends?

When you leave an employer, your group health insurance typically ends. You may be offered a group leaver policy or you can arrange individual cover. Acting before your employer scheme ends protects your medical history and avoids gaps in cover.

Is mental health cover included?

Most plans now offer mental health cover as a standard part of the plan or as an optional extra. The level of support varies by insurer, so it is worth comparing what is included.

Why does your location in the UK matter?

Insurers look at the cost of private hospitals in your area when setting premiums. A plan in London often costs more than one in Wales because hospital costs are higher in the capital. As insurance specialists, we check which insurers have the best hospital networks for your postcode.

How does making a claim work?

If you have a new medical condition, we guide you through the claims process. We help you understand the referral, pre-authorisation, and the difference between chronic and acute conditions. Having a professional to call when a claim is confusing is a major benefit of using a broker.

How much does a health insurance broker cost?

Nothing. We do not charge you a separate broker fee for our advice or comparison service. If you take out a policy through us, the insurer pays us a commission.

Using a broker does not mean we add a markup to your premium. In many cases the price is the same as going direct. In some cases, we may be able to secure a better deal or preferential offer depending on the insurer and policy available.

Do I need a health insurance broker or can I go direct?

You can go direct, but you will only see that one insurer's options. A broker vs going direct comparison usually favours using a broker because we compare leading UK health insurers, explain the differences in plain English and manage your policy year after year with no separate broker fee.
More questions? See our full health insurance FAQs.

Ready for Your Free Review?

Whether you are in London, Scotland, or Wales, we are here to help. Based at our Putney office, we support clients across the UK.

0203 859 1822

No obligation. Recommendations depend on your medical profile and insurer terms.

Need help choosing? Free comparison — no obligation
Call Now
Call Us